
A High-Frequency Leading Indicator Model Linking Memory Indices and PC/Smartphone Shipments
In technology markets, most of the attention goes to the shiny devices we can see and touch: PCs, laptops, smartphones, tablets. Yet the real heartbeat of those markets often lies in something far more invisible — memory. DRAM, NAND, and related storage components set the pace for production, shape margins, and quietly telegraph where demand is headed before shipment reports or earnings calls ever arrive. If you want to build an ETF or index derivative around AI storage and computing power, learning to read those memory signals is not just helpful; it is foundational.
This post explores the idea of a high frequency leading indicator model that links memory indicators to PC and smartphone shipments. Think of it as an attempt to translate the daily and weekly rhythms of memory pricing, inventory, and utilization into a forward-looking view on device markets and, by extension, on AI infrastructure themes. The goal is not to present a rigid, equation-heavy framework, but to sketch out a flexible, intuitive approach that investors and quants can adapt as markets evolve.
Why Memory Leads Devices
To understand why memory indicators might lead PC and smartphone shipments, it helps to zoom out for a moment. Memory is a core input into every modern computing device. Rising DRAM and NAND prices, tightening supply, or sudden shifts in utilization can make it more expensive and complicated to build PCs and smartphones at scale. These components are often ordered months ahead, with contracts reflecting expectations about future demand and production capacity. In effect, memory markets are continually digesting the forward plans of hardware manufacturers.
Because of this role, memory markets often move first. When device makers anticipate stronger demand or new product cycles, they ramp up orders, pushing up prices and straining supply. When they foresee softer demand, they cut back, leaving memory suppliers facing surplus inventory and price pressure. This makes memory indicators — prices, lead times, inventory data, utilization rates — natural candidates for leading signals on where shipments are headed next. They are like the early notes of a song that later becomes a full market cycle.
From Memory Indicators To A Leading Model
A high frequency leading indicator model is essentially a bridge between two worlds. On one side you have memory data that updates daily, weekly, or monthly: spot prices, contract prices, utilization rates, and production volumes for DRAM and NAND. On the other side you have PC and smartphone shipment data that typically comes out monthly or quarterly, sometimes with lags. The model’s job is to take the fast-moving memory information and turn it into a forward-looking signal about slower-moving shipments.
Building such a model does not require locking yourself into one strict methodology. Instead, you can think of it as a layered process:
- Identify a set of core memory indicators that are reliably available at high frequency.
- Map out the typical lead-lag relationships between those indicators and device shipments.
- Construct a composite index that weights the indicators according to their predictive power.
- Translate shifts in the composite index into probabilistic views on future PC and smartphone shipment trends.
The model does not need to produce a single, crisp number like “next quarter’s shipments will be precisely X units.” It can instead produce directional signals, confidence bands, or scenario probabilities that feed into broader ETF or index derivative strategies focused on AI storage and computing power.
Core Memory Indicators: The Ingredients
What counts as a memory indicator in this context? While the exact mix depends on data availability and investor preference, some common ingredients stand out:
- Spot and contract prices for DRAM and NAND: These reflect real-time tension between supply and demand and are often the first to respond to changes in device makers’ order behavior.
- Inventory levels at major memory producers: Rising inventories can signal weaker downstream demand or overproduction, while tightly managed inventories may indicate healthy demand or constrained capacity.
- Fab utilization rates: High utilization suggests strong demand or limited capacity; sharp declines often precede or coincide with shipment slowdowns.
- Lead times and backlogs: Longer lead times can signal that device makers are locked into aggressive order patterns, foreshadowing stronger or at least sustained shipments.
- Capital expenditure trends: While less high frequency, changes in planned spending on new capacity can hint at expectations about future memory demand.
Each indicator tells a slightly different story. Prices speak to immediate market tension. Utilization and inventory reflect operational decisions. Capex reveals strategic conviction. A high frequency model weaves these strands into a coherent signal that looks ahead to PCs and phones rather than back at them.
Lead-Lag Relationships: How Far Ahead Does Memory Speak?
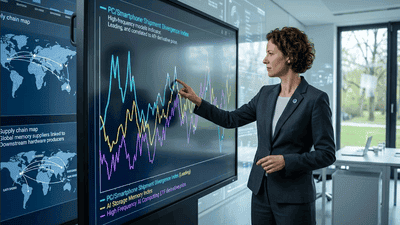
One of the subtler aspects of building a leading indicator model is choosing the right horizon. Memory prices might move weeks before shipment data, while utilization and inventory shifts could lead by months. In practice, device makers order memory with planning cycles that vary by product type and market conditions. A flagship smartphone line might have long, well-defined procurement schedules; more generic devices might respond more quickly to demand volatility.
To handle this complexity, it is useful to think in terms of overlapping lead horizons:
- Short-term leads (1–3 months): Often driven by spot prices, lead times, and incremental changes in orders.
- Medium-term leads (3–9 months): Influenced more by sustained trends in utilization, inventory, and capex decisions.
- Cycle-level leads (9–18 months): Linked to larger strategic moves, such as building new fabs or reorienting product roadmaps for AI-heavy devices.
A high frequency model does not need to pick one single horizon. Instead, it can track multiple lead relationships simultaneously, recognizing that memory markets can send fast, noisy signals and slower, more structural ones at the same time.
Composite Memory Signal: Turning Many Metrics Into One Voice
Once you have identified useful indicators and lead horizons, you need a way to combine them. A composite memory signal is a logical step. In simple terms, it is an index that blends multiple memory metrics into one synthetic value that is easier to interpret day by day or week by week.
A composite index might:
- Normalize each indicator to a common scale, such as deviations from long-term averages.
- Apply weights based on historical predictive power for shipments or based on qualitative judgment about which indicators are most central in the current cycle.
- Update the index at high frequency as new memory data arrives.
When the composite memory signal rises sharply, it might indicate tightening supply, strong demand, or both — a precursor to robust PC and smartphone shipments. When it falls, it could flag weakening orders, surplus inventory, or caution in device production. Crucially, the composite signal is not “truth”; it is a lens, a way of seeing, that needs to be interpreted with flexibility and context.
Linking The Signal To Shipments: From Lens To Forecast
The next step is to connect the composite memory signal to shipment outcomes. Here the model moves from description to inference. The question becomes: when the memory signal moves, how likely is it that shipments will follow, and on what schedule?
One flexible way to approach this is to think in terms of regimes and scenarios:
- Expansion regime: Memory indicators show rising prices, tightening inventories, and high utilization. In this environment, the model might assign high probability to rising PC and smartphone shipments over the next few quarters, with particular strength in AI-capable devices.
- Moderation regime: Memory signals are mixed or flat. The model may forecast more stable or mildly declining shipments, with manufacturers adjusting mix rather than overall volumes.
- Contraction regime: Memory indicators point to falling prices, rising inventories, and lower utilization. The model would expect shipments to weaken, especially in price-sensitive segments.
Because the model updates at high frequency, it can detect regime shifts relatively early and translate them into ETF or index derivative positioning decisions. The flexibility comes from acknowledging that regimes do not snap on or off with precision. They emerge, fade, and sometimes coexist across different parts of the memory and device landscape.
Implications For AI Storage And Computing Power ETFs
So far, we’ve looked at the linkage between memory indicators and PC/smartphone shipments in a fairly general way. But the original motivation was to understand ETF and index derivative strategies around AI storage and computing power. How does this leading indicator model feed into those themes?
AI infrastructure ETFs often hold a mixed basket of companies: memory producers, storage solution providers, data center operators, semiconductor firms, and sometimes device makers themselves. A high frequency memory-led model can help such ETFs:
- Adjust exposure between pure memory names and device-centric names as cycles evolve.
- Rotate between consumer device segments and enterprise or data center segments based on memory demand signals.
- Use index derivatives linked to memory prices or composite signals as hedges or tactical overlays.
In other words, the model becomes a bridge not only between memory metrics and shipments, but between physical markets and financial products. It informs how an AI storage and compute ETF tilts toward more cyclical or more structural components of the theme across time.
Index Derivatives As Expression Tools
Index derivatives — futures, options, swaps linked to memory indices or device shipment indices — can serve as the expression layer for this leading indicator model. Rather than constantly rebalancing physical ETF holdings, managers can use derivatives to quickly reflect model-driven views while maintaining a stable core portfolio.
For example:
- In an expansion regime, where memory signals point to rising shipments and strong demand, the ETF manager might use index futures or options to increase effective exposure to memory-heavy hardware indices without immediately changing spot holdings.
- In a contraction regime, derivatives can be used to hedge or reduce risk, overlaying short positions or protective options on indices that represent PC and smartphone markets.
- In a moderation regime, derivatives might be used more selectively, focusing on volatility strategies or relative value between memory indices and device shipment indices.
This derivative layer allows the high frequency model to influence portfolio behavior even when physical rebalancing is slower or more constrained by thematic purity. It also lets investors choose whether to express their views through outright ETF allocations, derivative overlays, or both.
Non-Linearities And Narrative: Keeping The Model Humble
It would be comforting to imagine that the relationship between memory indicators and device shipments is linear and stable. Reality is messier. Non-linearities abound: sudden breakthroughs in device design, geopolitical shocks affecting supply chains, regulatory changes, and shifts in consumer behavior all can disrupt neat correlations. A high frequency model must therefore be humble, designed with enough flexibility to handle surprises.
Narrative plays a role here as well. Markets are not just data processing machines; they are storytellers. A wave of optimism about AI in smartphones, for example, might encourage manufacturers to commit to aggressive memory orders even when some indicators are cautious. Conversely, a narrative of saturation in the PC market could dampen shipments despite supportive memory signals. The model’s leading power is strongest when the narrative and the memory data align; it is weaker when they diverge. Recognizing this tension is part of using the model wisely.
High Frequency Does Not Mean High Precision
Another important nuance: “high frequency” does not guarantee “high precision.” Updating the model daily or weekly can sharpen its responsiveness, but it does not magically eliminate uncertainty. In fact, high frequency data often includes more noise, short-term swings, and contradictory signals. One indicator might spike while another softens, leaving the composite signal in a gray zone.
The art lies in interpreting these high frequency moves in the context of broader cycles. Sudden jumps in spot prices might reflect short-term supply snarls, not fundamental demand changes. Brief dips in utilization could be maintenance-related, not evidence of weakening orders. A flexible model treats high frequency input as a set of clues, not commands. It combines statistical techniques with qualitative judgment, allowing ETF managers and analysts to contour their decisions rather than mechanistically following every blip.
Blending PC/Smartphone Cycles With AI Infrastructure Trends
One of the more intriguing aspects of linking memory indicators to PC and smartphone shipments is the way it reveals overlaps and divergences between consumer devices and AI infrastructure. On one hand, both domains rely on memory, often competing for capacity and influencing price cycles. On the other, AI infrastructure — data centers, training clusters, inference hardware — can follow different demand rhythms than consumer devices.
A high frequency memory-led model can help highlight these differences. If memory indicators show tightening supply driven mainly by AI hardware orders, PC and smartphone shipments might feel pressure even as overall memory demand remains strong. In that case, an AI storage and computing power ETF might tilt more toward data center and enterprise infrastructure, using derivatives or selective allocations to reduce exposure to consumer device makers. Conversely, if memory signals are driven by consumer refresh cycles while AI orders pause, the ETF might rebalance in the opposite direction.
Practical Use Cases For Investors And Analysts
For investors, the model is not just an abstract construct. It can inform concrete decisions:
- A long-term investor in AI storage and computing power ETFs might use the model to time incremental additions or trims, adding during memory-led expansion regimes and trimming when contraction regimes appear.
- A more tactical trader might use derivatives linked to memory or device indices to express short-term views generated by high frequency model signals.
- An equity analyst might integrate memory indicators into their coverage of PC and smartphone makers, using the leading model as a sanity check on company guidance and industry forecasts.
None of these uses require blind obedience to the model. They all treat it as one input among many — a structured way to listen to memory markets, but not the only voice in the room. That balance between reliance and skepticism is key to making high frequency leading indicators useful rather than overbearing.
Design Principles: Keeping The Model Alive
Because both AI infrastructure and consumer device markets evolve quickly, any leading indicator model should be treated as a living system, not a static formula. Several design principles help keep it alive:
- Regular recalibration: As new data arrives and cycles unfold, adjust indicator weights and regime definitions rather than assuming they are fixed.
- Transparency: Make the logic of the model clear to decision-makers using it, so they understand where its strengths and blind spots lie.
- Pluralism: Allow multiple signals — macro data, company-level information, narrative analysis — to coexist alongside the memory model.
- Scenario thinking: Use the model to generate scenario trees rather than single-point forecasts, encouraging flexible responses.
These principles do not turn high frequency data into a crystal ball, but they can make it a more reliable compass. In dynamic markets, the ability to adjust the model is just as important as its initial design.
Closing Thoughts: Listening To Memory’s Rhythm
A high frequency leading indicator model linking memory indicators and PC/smartphone shipments is, at heart, a way of listening. Memory markets — DRAM, NAND, storage capacity — have their own rhythm, distinct yet intertwined with the rhythms of device launches, consumer upgrades, and AI infrastructure buildouts. By attending to that rhythm, investors and ETF designers gain an early sense of when demand is rising, plateauing, or pulling back.
The model does not have to be rigid or single-toned. It can be pragmatic, interpretive, and adaptive, combining fast-moving data with slower trends and narrative context. For those building or using ETF and index derivative strategies around AI storage and computing power, such a model offers a useful bridge between the microstructure of memory markets and the macro picture of shipments and infrastructure cycles. It will not always be right; no model is. But by listening closely to memory and translating its signals thoughtfully, we stand a better chance of understanding how the next chapter of computing — in our pockets, on our desks, and in vast AI clusters — is likely to unfold.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?